


Any scrap car with outstanding finance enquiry must be resolved before Scrap Cars and Vans Bristol can responsibly remove the vehicle. A failed engine, accident or uneconomical repair does not automatically end the rights held by a finance provider.
Ownership depends on the agreement used to fund or supply the vehicle. Because Hire Purchase, Personal Contract Purchase, leasing and unsecured borrowing work differently, one answer cannot cover every case. Locate the contract and speak to the provider before attempting to scrap car with outstanding finance.
Identify the agreement before taking action
Read the finance documents and confirm the name of the product. Under Hire Purchase, the lender generally owns the vehicle until the final payment. MoneyHelper notes that an HP customer cannot sell or modify the vehicle during the agreement without the finance company’s permission.
PCP commonly follows a similar ownership structure until the required payments and any final balloon payment are completed. Personal Contract Hire is a lease, which means you are renting the vehicle. None of these arrangements normally allows you to scrap car with outstanding finance simply because repairs have become expensive.
An unsecured personal loan can be different
Borrowing money through a personal loan may leave you as the vehicle’s legal owner from the day of purchase. The debt remains payable, but it is usually attached to you rather than secured through the lender’s ownership of the car.
Check the actual paperwork instead of relying on how the monthly payment appears on a bank statement. Dealer-arranged finance contracts and ordinary bank loans can create very different rights. Knowing the distinction is essential when considering whether you may scrap car with outstanding finance.
Request an up-to-date settlement figure
Contact the lender and ask for the amount required to settle the agreement early. MoneyHelper recommends obtaining a settlement figure when ending PCP ahead of schedule. The figure may include more than the remaining monthly instalments, so do not estimate it yourself.
Compare the settlement amount with the likely value of the damaged or unwanted vehicle. When the debt exceeds the vehicle’s value, paying the finance from the scrap proceeds will leave a shortfall. Written confirmation that settlement ends the lender’s interest should be obtained before arranging to scrap car with outstanding finance.
Accident damage involves the insurer too
Notify the insurer and finance provider when the car has suffered serious accident damage. Insurers may inspect the vehicle, declare a total loss and handle the salvage as part of the claim. Independent collection could interfere with that process.
Mechanical failure should also be reported to the lender if the agreement remains active. Depending on the contract, the provider may discuss return, settlement, repair or another route. Only clear written permission should be treated as authority to scrap car with outstanding finance.
Voluntary termination is a separate process
Eligible customers under some regulated HP and PCP agreements may be able to use voluntary termination. MoneyHelper explains that this generally involves paying, or becoming liable for, half of the total contract amount. With PCP, that total includes the balloon payment.
Returning the vehicle under the lender’s instructions is not the same as having it destroyed. Voluntary termination does not hand ownership to the customer or create automatic disposal permission. Anyone struggling with affordability should seek guidance from the lender or a free debt-advice service instead of trying to scrap car with outstanding finance.
Evidence must be clear before collection
Retain the settlement letter or other proof showing that the lender’s interest has ended. Where the provider has agreed to destruction as part of a special arrangement, request written consent that identifies the registration and states what is authorised.
Scrap Cars and Vans Bristol may also require the V5C, photo identification, proof of address and evidence that you can dispose of the vehicle. A log book in your name is not enough if a lender remains the owner. These checks prevent an unauthorised scrap car with outstanding finance transaction.
Resolve first, arrange collection second
Start with the contract, then contact the lender for a settlement figure or instructions covering a severely damaged vehicle. Keep notes and written correspondence, and wait until the ownership position is definite before accepting a scrap quotation.
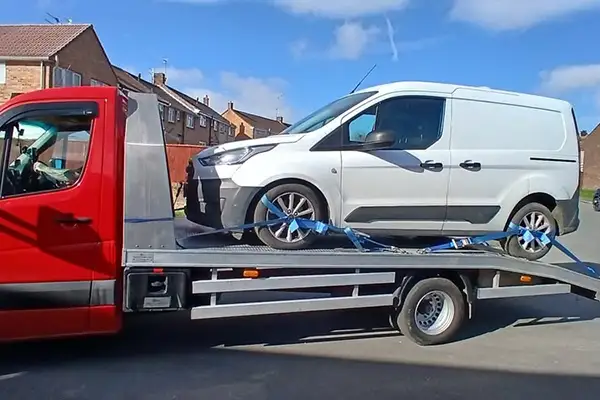
Once authority is established, Scrap Cars and Vans Bristol can assess the vehicle and plan recovery from an accessible Bristol location. Handling matters in this order allows a scrap car with outstanding finance to enter lawful disposal without ignoring the lender’s rights.
Useful external sources
• MoneyHelper: Ending a car finance deal early